Kids have big dreams for the future, but they change their minds often. Embark is the flexible savings plan that supports whatever path they pick.
Oct 9, 2026
Popular searches
At a glance:
A Trump account and an Embark 529 account are both investment plans for children that have tax benefits. But that’s where the similarities end. Let's get into the details.
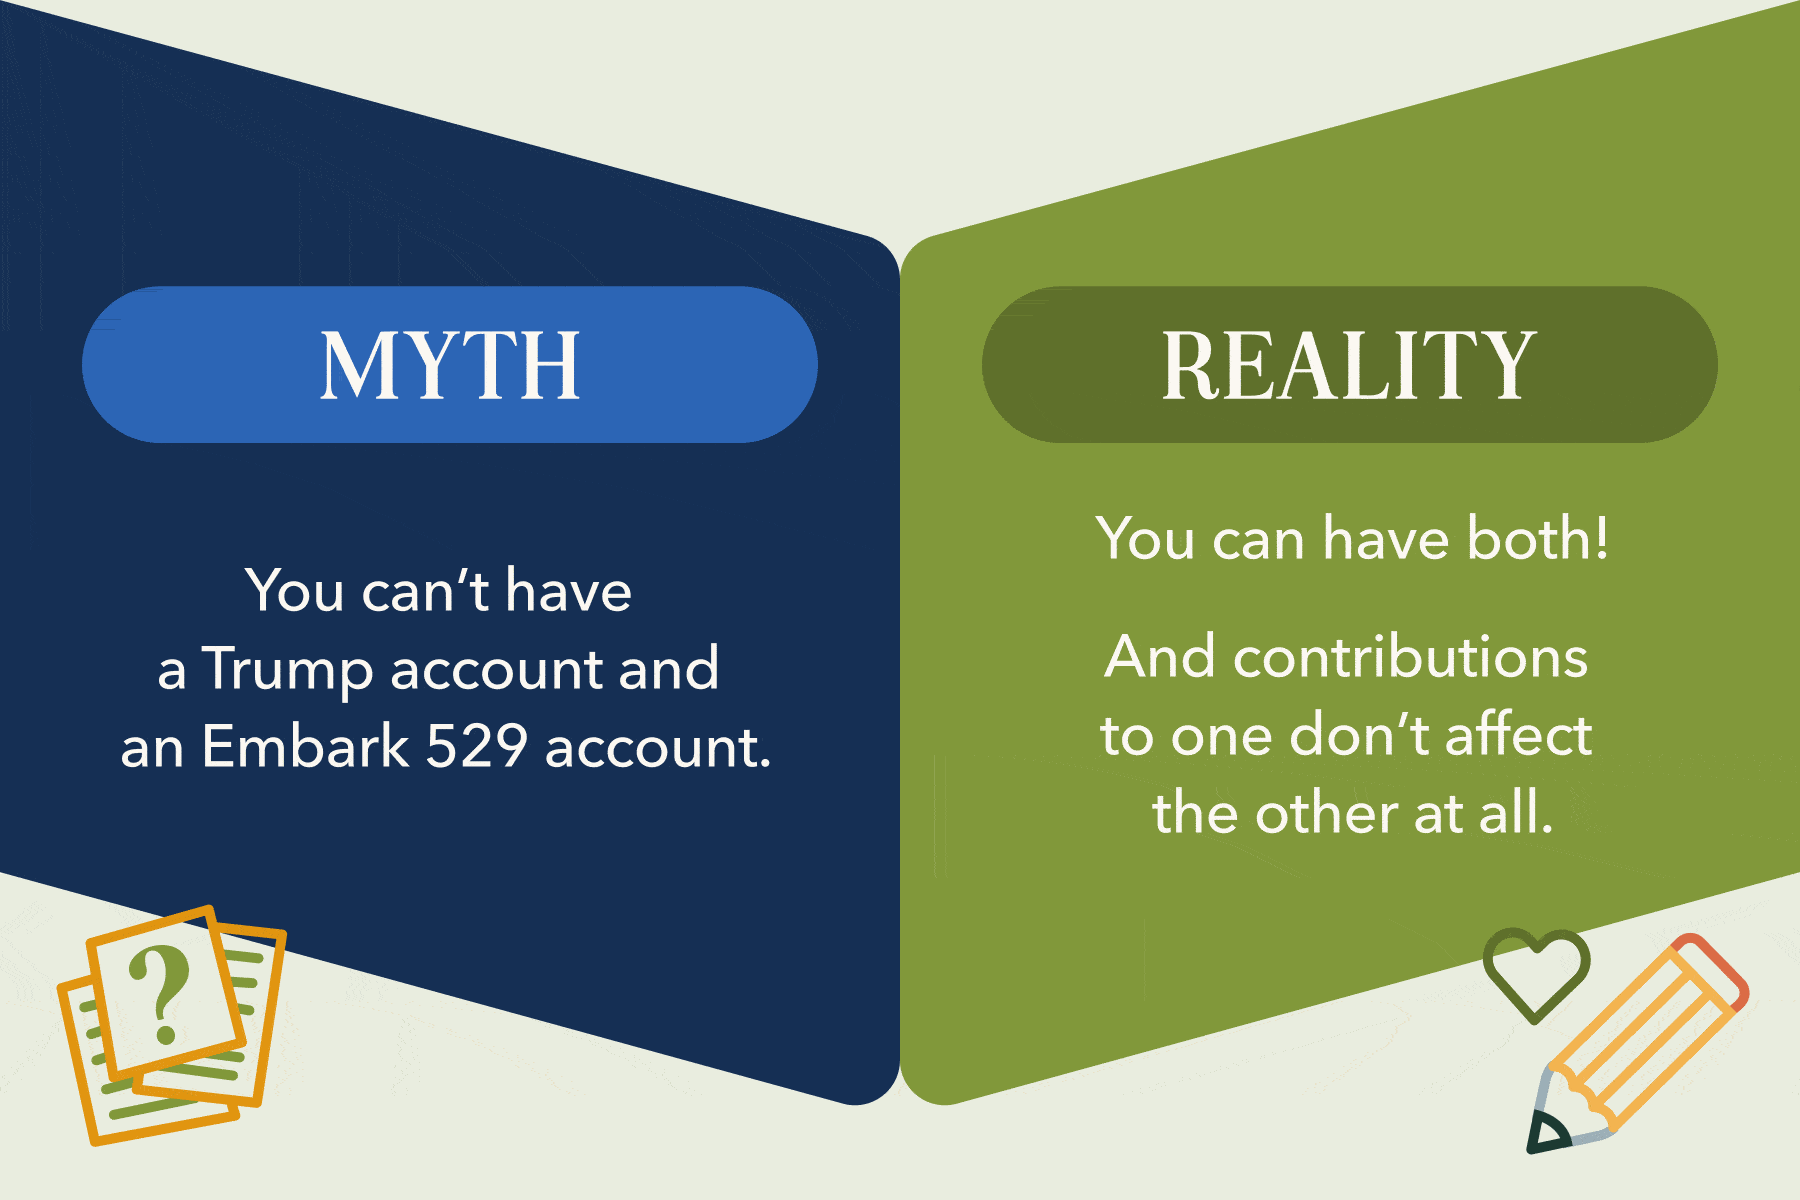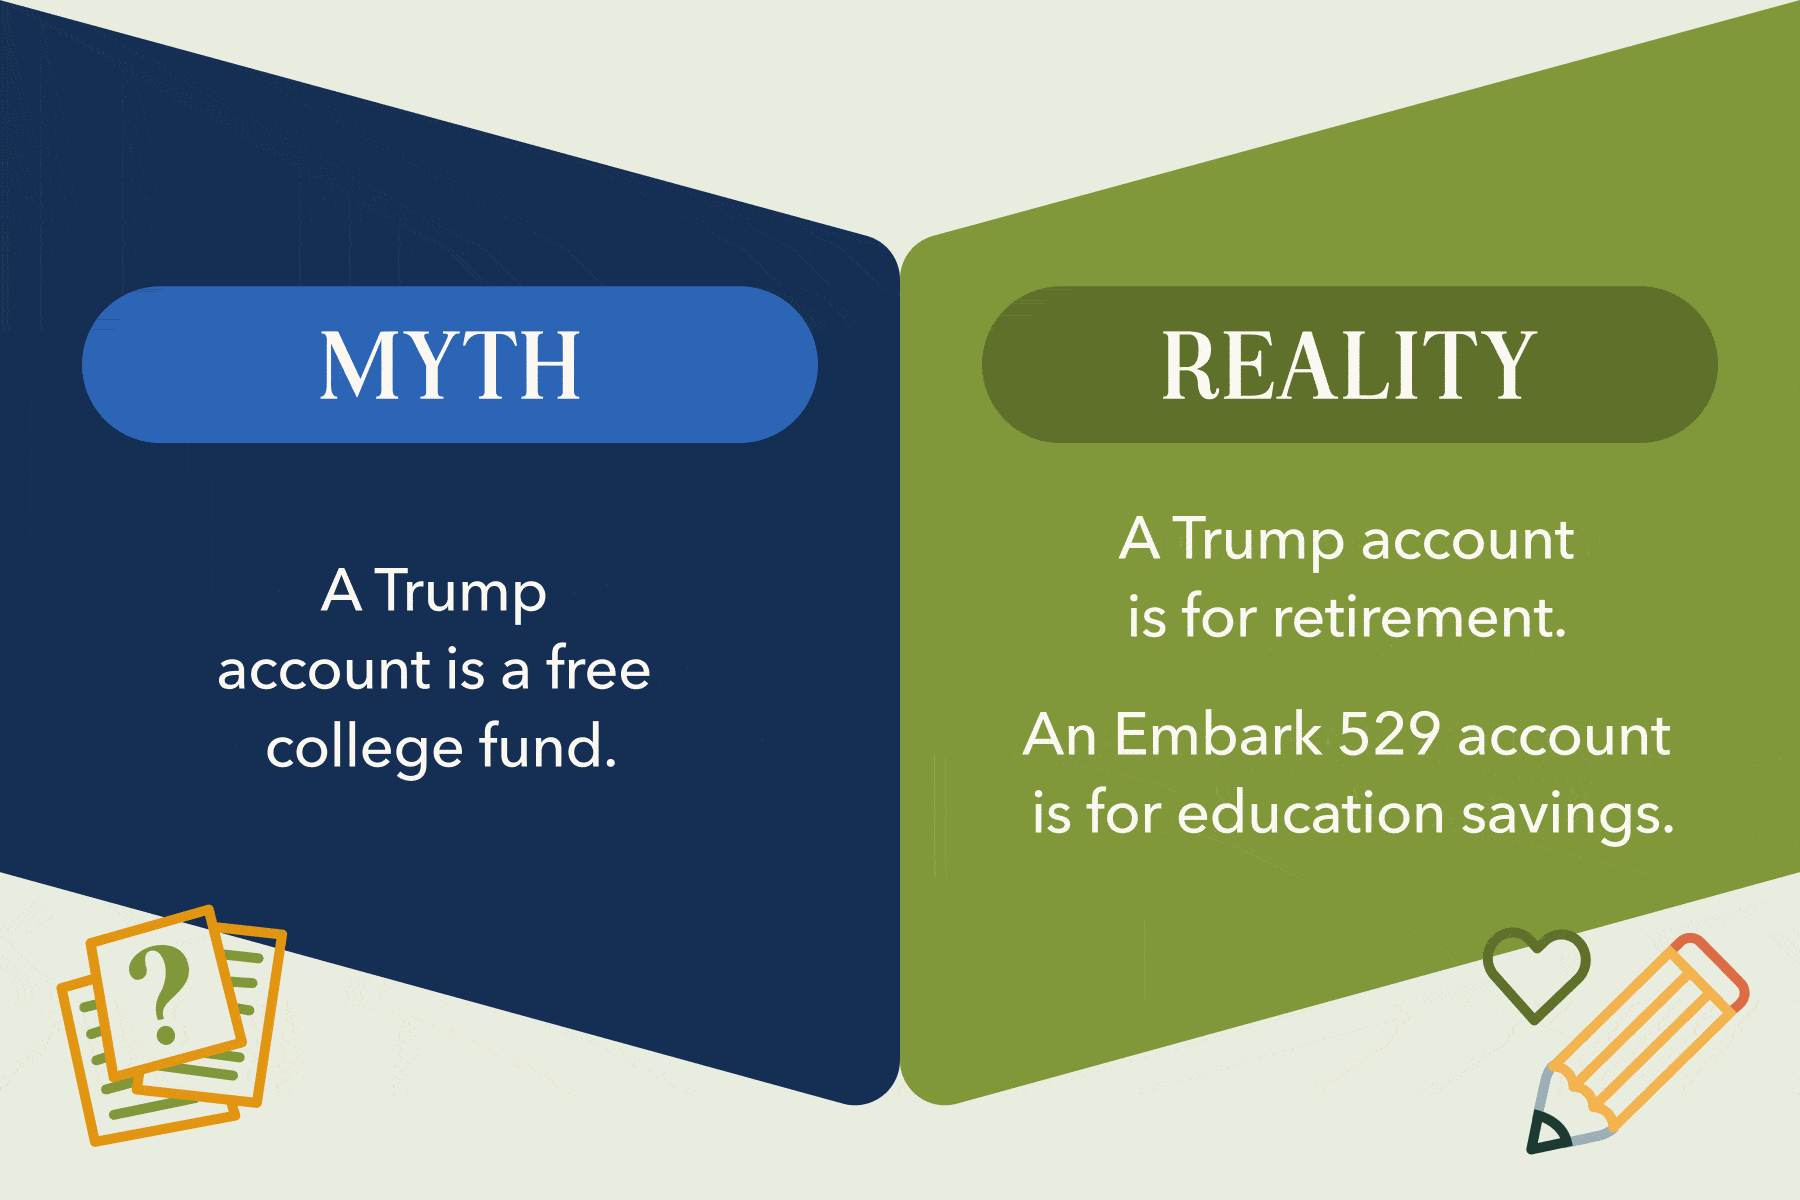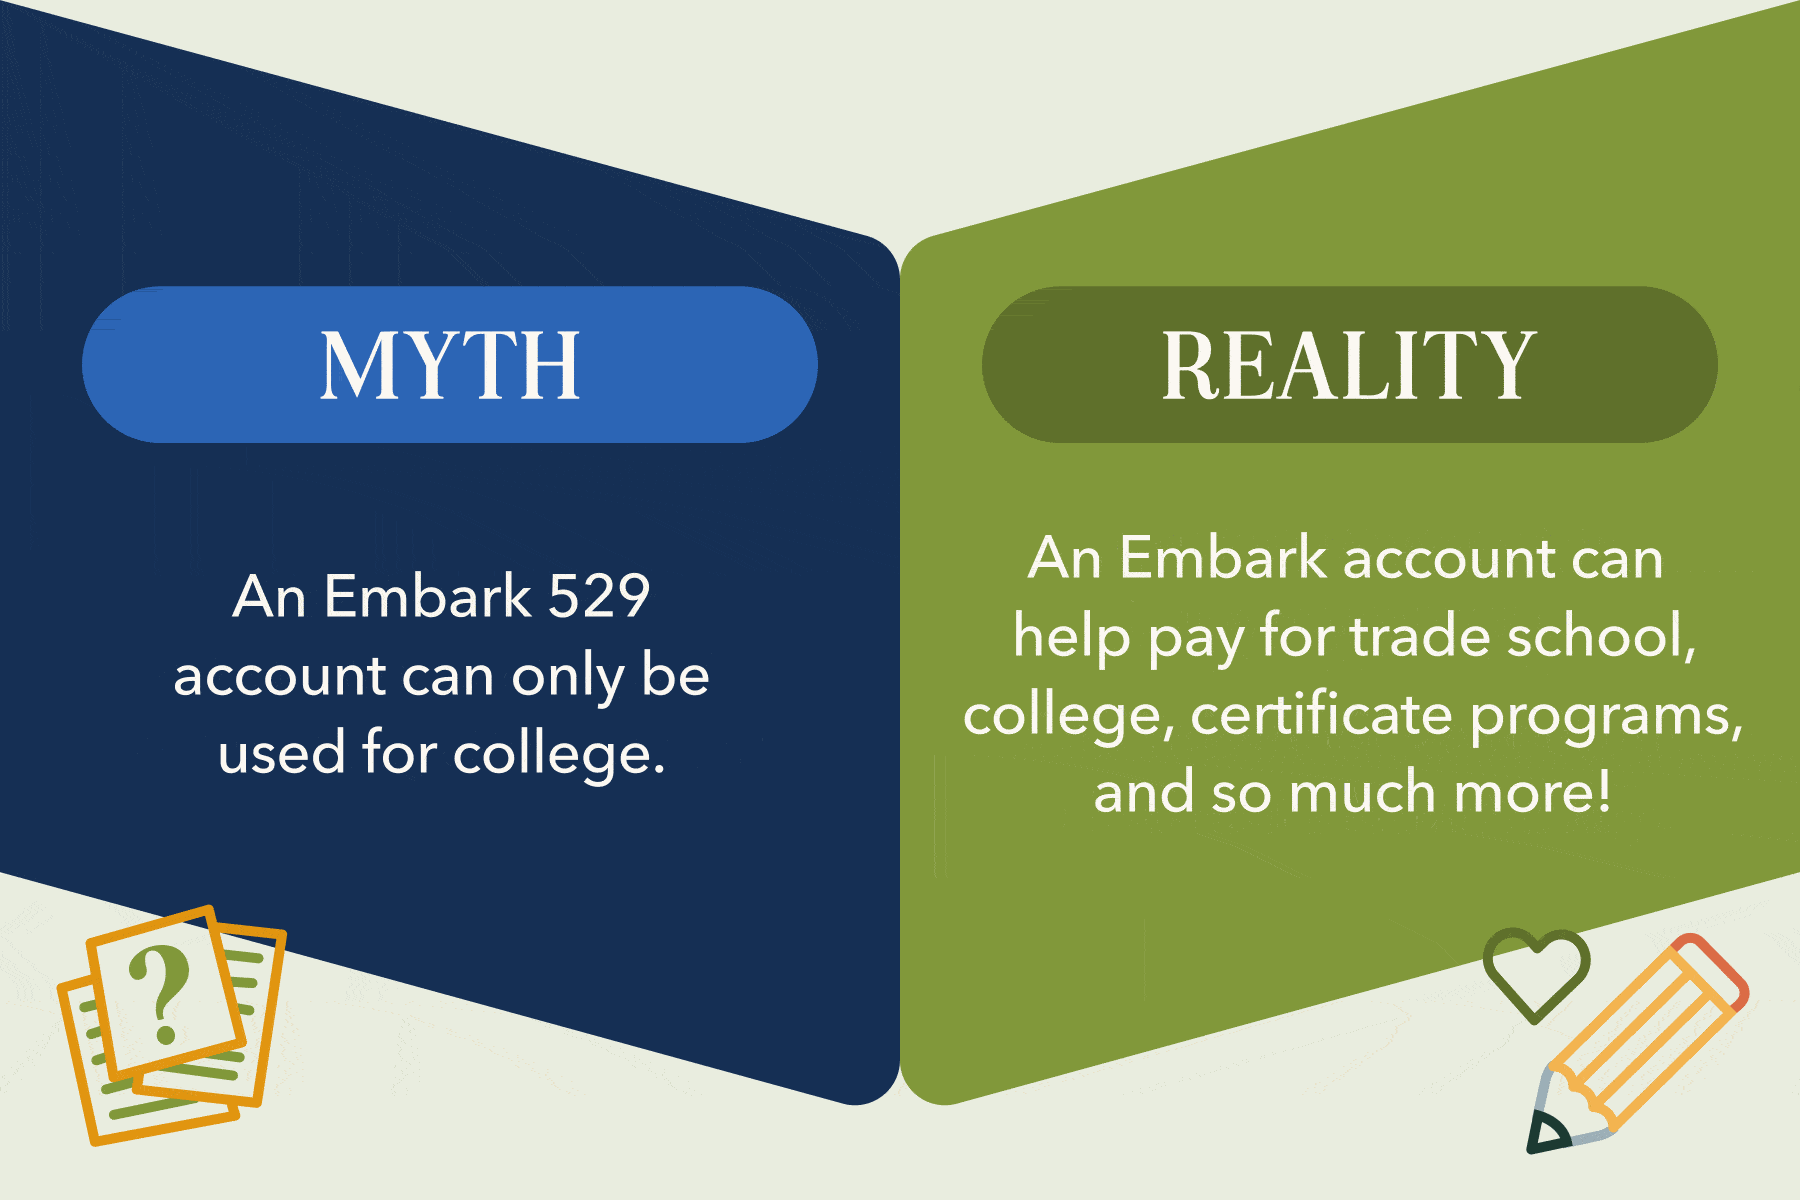
Also known as a 530A account, a Trump account is like an IRA for kids. It’s designed for retirement, so the funds you invest are locked away until your child turns 18. The account grows tax-deferred, and it transitions into a traditional IRA account after your kid turns 18. When your child accesses the money in a Trump account they’ll need to pay taxes on it.
529 plans, like Embark, are specifically designed to help families save for education. Parents and loved ones can open an account for a child and contribute over time. As the account grows, it can earn interest tax-free, helping your savings go further. When kids are ready for college, trade school, an apprenticeship, or another eligible educational path, you can withdraw the funds tax-free.
Right now, the federal government is giving families a one-time $1000 deposit when they open a Trump account for their kids. To qualify, children must be born between January 1, 2025 and December 31, 2028, be U.S. citizens, and have a Social Security number.
$1,000 for your kid’s retirement is a great offer! But keep in mind, money in a Trump account won’t be accessible to your child until they turn 18 and will be taxed later. So while $1,000 for their retirement is wonderful, it’s not designed to help them pay for school.
When it comes to saving for your kid’s education, an Embark 529 account was built for the job. Take a look at how Embark stacks up against a Trump account.
With an Embark 529 account, you can access the money whenever you need it for your child’s education. And if your child doesn’t go to school or doesn’t use all the funds, they can be transferred to an eligible family member or rolled into a Roth Individual Retirement Account (IRA) for your kid.
Trump accounts work a little differently. Your child generally can’t access the funds until they turn 18, when the account begins functioning more like a traditional IRA. While having a Trump account shouldn’t affect your child’s financial aid eligibility, making withdrawals could. Money withdrawn from the account may count as income on the Free Application for Federal Student Aid (FAFSA), which could affect the amount of financial aid your child receives.
You can withdraw funds from your Embark 529 account tax-free when using them for educational expenses, including for college, certificate programs, and trade school. This also includes qualified expenses like books, school supplies, and room and board.
When withdrawing funds from a Trump account, your child could face a 10% penalty for early withdrawals if they use the funds before age 59½. While education expenses can be exempt from this 10% penalty, they’d still pay standard income taxes on the $1000 seed money, any government matches, and all the investment growth the account has earned.
As Oregon’s official 529 plan, Embark gives local families a few extra perks and programs for saving. In addition to the tax-free account growth and tax-free withdrawals, Oregon families that contribute to their Embark account can earn an annual refundable tax credit worth up to $380 for joint filers and $190 for single filers every year.
Plus, families that open an account for their child before their first birthday or while they’re in kindergarten can get a $100 boost with our Baby Grad and Kinder Grad programs. And with our BottleDrop partnership, you can easily turn your recycling deposits into education savings.
Signing up is simple, and saving early gives your money more time to grow.
Kids have big dreams for the future, but they change their minds often. Embark is the flexible savings plan that supports whatever path they pick.
Oregon’s “Baby Grad” bonus offers families a $100 contribution when they open an Embark account before their child’s first birthday with as little as $25.
As you soak up the final days of summer vacation, it’s the perfect time to think about what comes next. Embark is here to help you start the year right.